
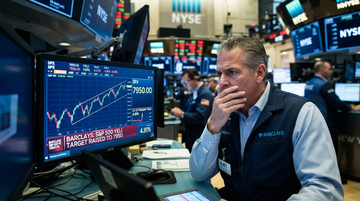
Barclays 2026 S&P 500 target
7,950
Raised from 7,800 on Sep 9, 2026; +3.6% above Sep 8 close of 7,673.52
Implied forward P/E on the new target
21.8x
$7,950 ÷ $365 EPS estimate (raised from $337); below current ~20-21x forward
Barclays 2026 EPS growth assumption
30.8%
Implies 2025 EPS base near $279; growth led by technology
Q2 S&P 500 beat rate
86%
492 of S&P 500 reporters topped estimates vs. 67.5% long-term average
10-year Treasury yield
4.81%
Sep 9, 2026; 16 bps above HSBC's 4.65% end-2026 forecast
Brent crude
$100.66
Sep 9, 2026 settle; first close above $100 since late July on U.S.–Iran tanker strikes
The Math
7,950 Doesn't Need the Multiple to Stretch—It Just Needs EPS to Land
Barclays lifted its year-end S&P 500 target from 7,800 to 7,950, a 1.9% raise. Headlines will treat that as a small tweak. The real move sits underneath: the bank raised its 2026 EPS estimate from $337 to $365, an 8.3% upgrade that implies 30.8% earnings growth off a 2025 base near $279. Divided into the new price target, the implied forward P/E is roughly 21.8x—below the S&P 500's current trailing P/E of 26.1x and roughly in line with its 20-21x forward band as of September 8. In other words, Venu Krishna's team isn't asking investors to pay up; it's asking earnings to keep showing up.
There is a reason that posture matters. The S&P 500 entered September 8 at 7,673.52—down 0.58% on the day and 1.8% below its all-time high of 7,816.70. The index is up 12.1% year to date, and trailing earnings power has lifted roughly 47% in Q2 per FactSet's blended growth rate. With the S&P 500 IT sector at 7,014 and semis expected to grow earnings 144% this year, Barclays is buying a quarter in which the earnings tape is doing the work the multiple no longer has to do.
Strategist Scoreboard
Barclays Is Quietly the Cheapest 8,000-Era Call on the Board
| House | Target | 2026 EPS used | Implied fwd P/E | Last update |
|---|---|---|---|---|
| Barclays (Venu Krishna) | 7,950 | $365 | 21.8x | Sep 9, 2026 |
| Fundstrat (Tom Lee) | 8,000 | n/a | ~21.9x* | Jun 25, 2026 |
| Goldman Sachs | 8,000 | $340 | 23.5x | May 27, 2026 |
| HSBC | 8,100 | $365** | 22.2x | Sep 7, 2026 |
| Morgan Stanley | 8,000 | n/a (mid-27 8,300) | n/a | May 2026 |
Barclays's 7,950 is the lowest year-end print among the major houses—and the cheapest on its own math. Using the updated $365 EPS, HSBC's 8,100 implies 22.2x forward, while Goldman Sachs's 8,000 implies 23.5x on its older $340 estimate. Tom Lee's 8,000 base case prices in roughly the same multiple as Barclays but assumes a path toward 8,400–8,800 in a stronger scenario. Stifel, by contrast, is sitting at 7,800. Barclays isn't bearish; it's just the only house that bothered to re-run the EPS first.
The Risk Layer
Oil Above $100, Yields Above the Forecast, and Two Officials Pulling in Opposite Directions
Three macro headwinds complicate the Barclays call, and all three are happening at once. Brent crude settled at $100.66 on September 9 after the U.S. struck three Iranian oil tankers over the weekend, the first close above $100 in six weeks. The 10-year Treasury yield touched 4.812% intraday before closing at 4.786%, already 16 basis points above HSBC's end-2026 forecast of 4.65%—the bank's own analysts had to walk their target higher on September 7, citing a higher structural floor for long yields.
- Warsh-Bessent tug-of-war: Fed Chair Kevin Warsh used his August 28 Jackson Hole remarks to push for less forward guidance and rate decisions based on data; markets are now pricing 58.4% odds of a September 15-16 hike to 3.75–4.00%, with UBS calling for two hikes this year and Macquarie moving its first hike to September from December.
- Bessent's bond-buying push: Treasury doubled long-dated buybacks to at least $4 billion per operation from September 9 through November 4, and the 30-year yield hit its highest since 2007 anyway. Critics inside the Fed community have called the move 'artificial yield suppression' and 'window-dressing.'
- Oil-inflation pass-through: August CPI prints September 11; economists expect a 3.4% headline. A hot number seals the hike probability higher and undoes both Bessent's buyback narrative and a chunk of the AI-led earnings optimism by reminding markets that energy is a tax on margins.
What's Holding the Bid
A $1.55 Trillion Buyback Bid and an 86% Beat Rate Are Doing the Heavy Lifting
The bull case isn't in the multiple—it's in corporate behavior. S&P 500 companies announced $665 billion in buybacks through early 2026, with full-year authorizations on track for $1.55 trillion, eclipsing the $1.153 trillion global record set in 2025. Microsoft alone returned $12.7 billion to shareholders in its fiscal Q2. Goldman Sachs delivered record Q2 net revenues of $20.34 billion with EPS of $20.98, up 92% year over year on a 72% surge in equities trading. ExxonMobil's quarterly profit more than doubled to $14.5 billion; Chevron's nearly quadrupled to $12.1 billion. The Q2 beat rate of 86% versus a 67.5% long-term average is what justifies Barclays raising EPS by 8.3%, and the buyback authorization wave is what turns each beat into a per-share number that compounds.
Implied multiples on each strategist's 2026 S&P 500 target
Forward P/E = price target ÷ house's 2026 EPS estimate; lower is cheaper relative to that house's own earnings assumptions
Unit: x forward earnings
Barclays (7,950 / $365)
21.8
HSBC (8,100 / ~$365)
22.2
Goldman (8,000 / $340)
23.5
Current S&P 500 trailing P/E
26.1
Sector Rotation
Utilities Just Lost Their Bull Case—Energy, Banks, and AI Megacaps Pick Up the Slack
The same note that lifted the index target downgraded the utilities sector to Neutral from Positive, citing the failure to advance wildfire liability reform and state-level opposition to data-center permitting. That matters because utilities were the rate-sensitive hedge against the Warsh-Bessent policy mess; removing them from a positive call says Barclays expects the AI capex cycle—not bond proxies—to keep the bid under the index.
| Company | Q2 metric | Result | Source |
|---|---|---|---|
| NVIDIA | Revenue (ended Jul 26) | $96.2B, +106% YoY | NVIDIA Q2 FY27 release, Aug 26, 2026 |
| Microsoft | Revenue / Azure | $81.3B, +17% YoY; Azure +38% CC | Microsoft FY26 Q2 release |
| Goldman Sachs | Net revenue / EPS | $20.34B / $20.98 (record) | Goldman Sachs Q2 2026 release |
| ExxonMobil | Net income / EPS adj. | $14.5B / $3.52 | ExxonMobil Q2 2026 release |
| Chevron | Net income / EPS adj. | $12.1B / $6.06 (nearly 4x YoY) | Chevron Q2 2026 release |
The Horizon
Days–Quarters: 7,950 Lives or Dies on the September 11 CPI Print
Two dates dominate the near-term path. The August CPI release on September 11 will either ratify Warsh's hawkish lean or soften it; a print at or above 3.4% year-over-year keeps the September 15-16 hike live and pressures the 10-year above 4.8%. The FOMC decision two business days later resolves the binary. If the Fed holds, Barclays's call becomes the path of least resistance: cheap multiple, 30% EPS growth, 86% beat rate. If the Fed hikes, the bond market re-prices higher and the 7,950 target becomes a ceiling until EPS catches up.
Over one to three years, the call looks more durable. Goldman Sachs projects 2027 S&P 500 EPS at $385; if Barclays's 30.8% growth proves conservative and the index compounds at, say, 12%, the 2027 target of 8,800 implies a forward P/E of roughly 22x on $400 of earnings—comfortable relative to a 10-year yield expected to settle near 4.75% by HSBC and well below current trailing multiples. The bigger structural risk isn't the Fed or oil; it's whether AI capex converts to free cash flow at the pace implied by NVIDIA's 106% revenue growth and Microsoft's 26% Cloud growth. If that conversion slips, every house—Barclays included—will be revising down, not up.
Investable takeaway
- Q2 revenue of $96.2B (+106% YoY) is the single largest contributor to Barclays's 30.8% 2026 EPS growth assumption
- Forward P/E of ~25.6x against a 21.8x index target leaves room for the stock to lead the 7,950 path
- Watch Q3 (reported late November) for any softness in data-center capex commentary from hyperscaler customers
- FY26 Q2 Cloud revenue of $51.5B (+26%) and Azure +38% constant-currency underpin the AI-capex-to-earnings bridge
- Returned $12.7B to shareholders in Q2 alone, a microcosm of the $1.55T 2026 buyback wave that holds the bid
- Copilot monetization and Azure AI services growth are the next data points that decide whether 7,950 holds or rips to 8,000
- Q2 profit more than doubled to $14.5B as Brent held near $100; forward P/E of 14.9x is among the cheapest in the index
- Oil at $100 flows directly to revenue per barrel with operating leverage on existing upstream capacity
- Iran-tanker escalation keeps Brent bid; a $90 print would erase roughly a third of the beat that lifted Q2 EPS
- Q2 profit nearly quadrupled to $12.1B on Iran-war oil prices; EPS adj. of $6.06 vs. $1.55 a year earlier
- Lower leverage and Gulf of Mexico exposure make it more sensitive to Brent sustaining above $100 than integrated peers
- Capital-return cadence through the year-end earnings season is the next read on whether $100 oil converts to per-share growth
- Record Q2 net revenue of $20.34B and EPS of $20.98 (+92% YoY) came on a 72% surge in equities trading
- Trading desks benefit directly from VIX expansion if the Bessent-Warsh standoff drives September-October volatility
- Forward P/E of 14.0x leaves room to re-rate as 2026 buyback authorizations and a steeper yield curve compound
- Q2 2026 trading revenue hit a record alongside Goldman's, with equities at $6.0B and FICC also strong
- Net interest margin holds up better than peers if Warsh delivers a September hike instead of a cut
- The 1.55T buyback tide and a steeper curve benefit JPM's multiple most inside the bank cohort
- Barclays downgraded the utilities sector to Neutral, citing the failure of wildfire liability reform and data-center permitting pushback
- Removes the rate-sensitive bond proxy that portfolios typically pair with the AI trade when yields rise
- Watch Q3 earnings and Florida rate-case outcomes for any re-rating opportunity if the sector call softens